How Card Payments Work in Canada: The Parties Behind Every Transaction
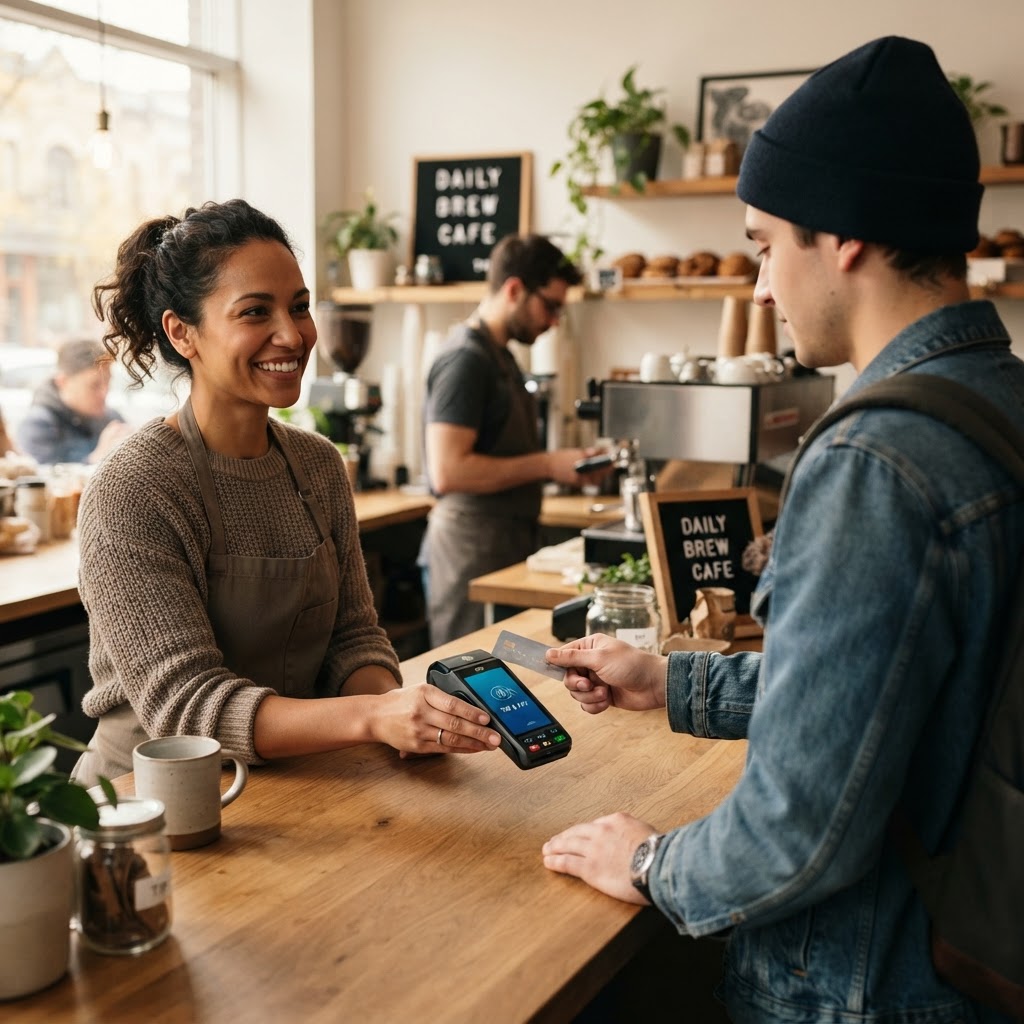
When a customer taps their card or enters payment details, a complex, multi-step digital handshake occurs in seconds to verify funds and move money. Understanding how card payments work Canada is essential for any business owner, as it involves a network of financial institutions, card networks, and processors working together to ensure every transaction is secure, authorized, and settled.
Key takeaways
- The Ecosystem: Canadian payments rely on a secure network involving the cardholder, the merchant, the acquiring bank, the card network (e.g., Visa, Mastercard), and the issuing bank.
- Interac Dominance: According to Payments Canada, credit cards led transaction volume in 2024 with 7.5 billion transactions, while Interac Debit remains a cornerstone of the Canadian retail experience.
- Interchange Fees: On credit card transactions, a significant portion of the cost is "interchange," which is set by card networks and paid to the card-issuing bank.
- Transparent Pricing: Many merchants overpay due to hidden fee tiers; Tap2Pay offers transparent, flat-rate or interchange-plus pricing that typically saves Canadian businesses 15-30%.
The anatomy of a card transaction
When a customer initiates a payment, the process moves through three distinct phases: authorization, clearing, and settlement. First, the terminal sends the encrypted card data to the merchant’s payment processor. The processor routes this request to the card network (like Visa or Mastercard), which then contacts the customer’s issuing bank to verify that the account is valid and has sufficient funds. Once the bank approves the transaction, an authorization code is sent back to the terminal, completing the "authorization" phase. Clearing and settlement follow, where the transaction details are batched and the actual funds are transferred from the issuing bank to the merchant’s account. At Tap2Pay, we simplify this by providing robust, Nuvei-powered processing that ensures these handshakes happen reliably, allowing you to focus on your customers rather than the technical backend.
How to accept card payments in Canada
Accepting payments requires a structured approach to ensure compliance and cost-efficiency. Follow these steps to get your business ready:
- Establish a Merchant Account: You need a dedicated account to hold funds before they are deposited into your business bank account.
- Select Your Hardware: Choose reliable, secure hardware. Tap2Pay provides advanced PAX smart terminals that support chip, PIN, and contactless payments, ensuring you are ready for modern consumer habits.
- Configure Your Payment Gateway: For e-commerce, ensure your website is connected to a secure gateway that encrypts customer data.
- Review Your Fee Structure: Avoid "bundled" pricing that hides high markups. Look for transparent interchange-plus models.
- Test and Go Live: Perform test transactions to ensure your terminal or gateway communicates correctly with the processing network.
What is the role of the payment processor?
A payment processor acts as the vital bridge between your business and the financial institutions that move money. When a customer pays, the processor securely transmits the transaction data, manages the communication between the card networks and your bank, and ensures that the funds are deposited into your account. Without a processor, a merchant would have to build direct, individual connections with every major bank and card network—a logistical impossibility for most businesses. By leveraging a professional processor, you gain access to secure, PCI-compliant infrastructure that handles the heavy lifting of fraud detection and data encryption. Tap2Pay serves as this essential partner, providing Canadian merchants with the technology and support needed to navigate the complexities of the payment landscape without the burden of long-term contracts or hidden fees.
Understanding the cost of processing
The cost of processing is often misunderstood, leading many merchants to pay more than necessary. In Canada, your processing cost is generally composed of three parts: interchange fees (paid to the card-issuing bank), assessment fees (paid to the card network), and the processor’s markup. While interchange and assessment fees are non-negotiable and set by the networks, the processor’s markup is where you have room to negotiate. Many providers inflate this markup with "hidden" tiers or complex surcharges. At Tap2Pay, we believe in radical transparency. We provide clear, predictable pricing models that eliminate the guesswork, helping you keep more of your hard-earned revenue. If you are tired of confusing statements, get a free quote to see how our transparent approach compares to your current provider.
Frequently Asked Questions
What is the difference between Interac Debit and credit cards?
Interac Debit transactions are processed directly through the Canadian banking system, often resulting in lower costs for merchants compared to credit cards. Credit card transactions involve international networks like Visa or Mastercard, which charge interchange fees that vary based on the card type and rewards program.
Are there specific rules for surcharging in Canada?
Yes. While some surcharging is permitted on credit cards, there are strict rules regarding disclosure and caps. Notably, you cannot apply a surcharge to Interac Debit transactions. Always consult with your payment provider before implementing any surcharges to ensure you remain compliant with provincial and network regulations.
How long does it take for funds to settle?
Settlement times vary depending on your processor and the payment method used. Most standard card transactions settle within 1–3 business days. Some modern solutions, including those utilizing direct-from-bank transfers, can offer faster settlement times. Tap2Pay works to ensure your funds are deposited as quickly as possible to maintain your cash flow.
Conclusion
Mastering how card payments work Canada is a competitive advantage for any business owner. By understanding the roles of the various parties—from the issuing banks to your payment processor—you can make informed decisions about your hardware, your pricing model, and your overall financial health. Whether you are upgrading your our terminals or looking for a more transparent pricing structure, Tap2Pay is here to support your growth with local, bilingual Canadian service. Ready to optimize your payment processing? Get a free quote today and join the thousands of Canadian merchants who have switched to a simpler, more cost-effective solution.
Reviewed by Tap2Pay's Canadian merchant services specialists. Updated 2026.