Interac Tap Payments: A Merchant's Guide to Accepting Debit Contactless
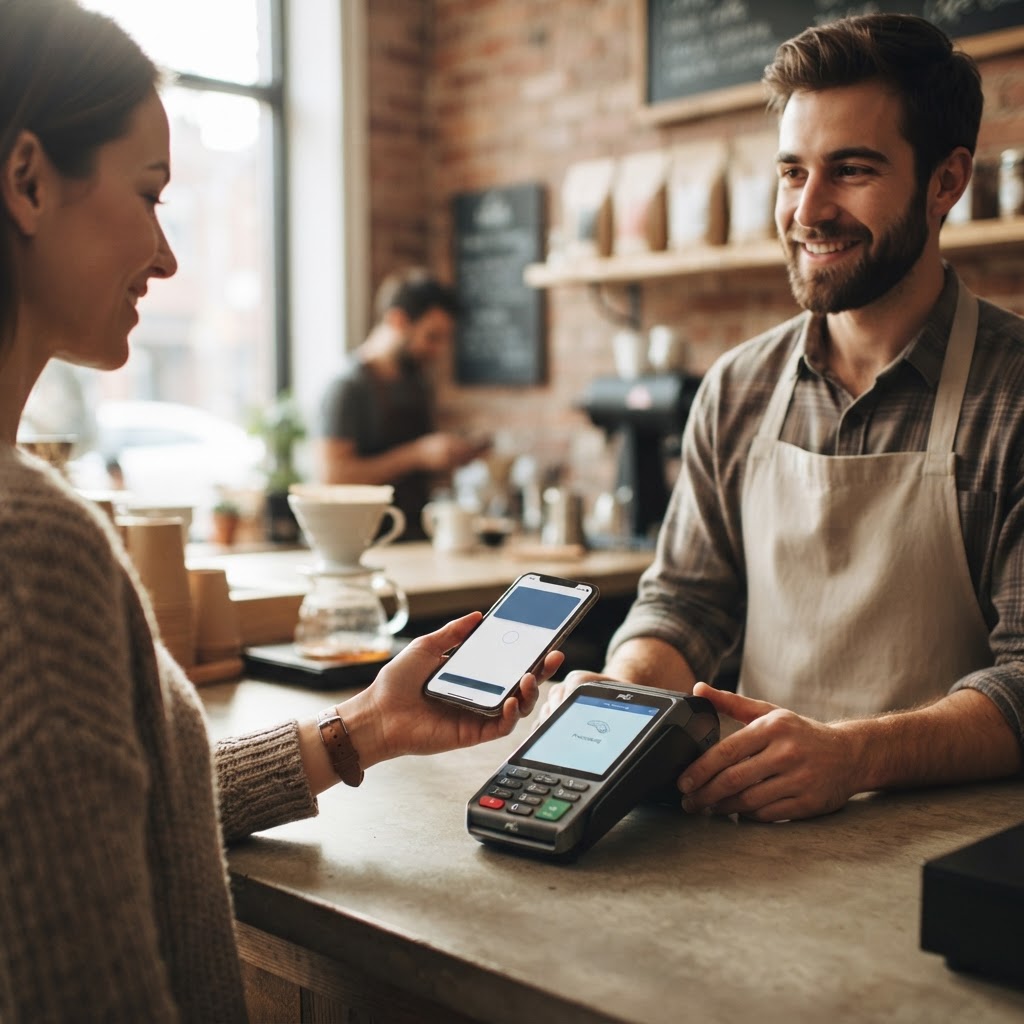
Interac tap payments allow Canadian consumers to pay for goods and services in seconds by tapping a debit card, smartphone, or wearable over a payment terminal using Near Field Communication (NFC) technology. Settled instantly on Canada’s domestic debit network, these transactions clear directly from the cardholder's bank account, giving merchants immediate settlement, protection from traditional chargebacks, and significantly lower processing costs compared to credit cards.
Key takeaways
- Interac tap transactions run on flat fees rather than percentages: Unlike credit card interchange rates that take 1.5% to 3.5% of gross sales, Interac debit transactions typically cost Canadian merchants a flat rate of roughly $0.05 to $0.15 CAD per transaction regardless of ticket size.
- The default contactless limit in Canada is $250 CAD: Contactless debit card payments are capped at $250 CAD per tap without a PIN, while smartphone transactions authenticated via biometrics (Apple Pay, Google Pay) can exceed this limit depending on the card issuer.
- Interac tap payments eliminate credit-style chargebacks: Because transactions require real-time bank account verification and cryptographic card authentication, merchants face virtually zero chargeback risk on standard in-person debit taps.
- Cumulative offline limits periodically trigger PIN requests: For consumer fraud prevention, Interac cards automatically prompt for a Chip and PIN insertion once a cumulative contactless spending limit (typically $200–$500 CAD) is reached across consecutive taps.
- Modern standalone smart terminals support both card and wallet debit taps: Equipping your business with modern, standalone hardware ensures seamless acceptance of Interac Flash, digital wallets, and dual-network cross-border cards without complex configurations.
What are Interac tap payments and how do they work?
Interac tap payments—historically branded as Interac Flash—are contactless debit transactions routed directly through Canada’s proprietary, interbank debit network.
When a customer holds an enabled debit card or mobile wallet within four centimetres of an NFC-equipped terminal, the terminal creates an encrypted radio frequency link to exchange transaction credentials. Unlike American debit cards that routinely run over international Visa or Mastercard credit card rails, Canadian debit runs over its own sovereign infrastructure established by Canada's major financial institutions.
The transaction workflow executes in three steps:
- Request: The terminal transmits the transaction total in Canadian dollars to the card's microchip or digital wallet token.
- Authentication: The card or phone verifies account validity and confirms that offline tap spending parameters have not been exceeded.
- Settlement: The Interac network routes the authorization directly through the customer’s bank (RBC, TD, Scotiabank, BMO, CIBC, Desjardins, or credit unions). The funds are reserved immediately and deposited directly into the merchant's settlement account.
Because the funds transfer directly between bank accounts, the merchant takes on no credit risk, eliminating the multi-day float and chargeback disputes common to credit card processing.
How much do Interac tap payments cost Canadian merchants?
Interac debit transactions are significantly cheaper to accept than credit cards because they are billed primarily on a flat, per-transaction fee rather than a percentage of the total transaction value.
When a customer taps a premium rewards credit card (such as a Visa Infinite Privilege or World Elite Mastercard), the merchant pays an interchange rate that often ranges from 1.65% to 2.40%, plus processor markups. On a $100 CAD purchase, a premium credit card can easily cost $2.20 to $3.00 CAD in processing fees.
In contrast, Interac charges an underlying wholesale network fee—usually just a few pennies per transaction. Your payment processor packages this network cost into your merchant service fee, which typically ranges between $0.05 and $0.15 CAD flat per transaction.
| Feature / Fee Element | Interac Debit Tap | Visa / Mastercard Credit Tap | | :--- | :--- | :--- | | Wholesale Network Rate | ~$0.0075 to $0.035 flat wholesale fee | 1.00% to 2.40%+ percentage interchange | | Average Final Cost | Flat $0.05 – $0.15 CAD | 1.50% – 3.20% of ticket volume | | Cost on a $20 CAD Sale | ~$0.08 CAD | ~$0.40 – $0.55 CAD | | Cost on a $200 CAD Sale | ~$0.08 CAD | ~$4.00 – $5.50 CAD | | Chargeback Vulnerability | Virtually Zero (Final settlement) | High (Friendly fraud, unauthorized use) | | Digital Wallet Surcharge | None (Same debit flat rate) | Standard credit network interchange |
While the underlying network fees are inherently low, some payment processors bundle debit transactions into expensive, tiered pricing structures (such as "non-qualified" surcharges) or inflate flat rates up to $0.25 CAD or more. At Tap2Pay, merchants receive completely transparent, wholesale-direct processing powered by Nuvei infrastructure. By eliminating hidden monthly junk fees and bloated debit margins, Canadian merchants typically save 15% to 30% on their overall payment processing bills. Review our straightforward terms on our pricing page.
What are the transaction and spending limits for Interac contactless?
The standard contactless tap limit for physical Interac debit cards in Canada is $250 CAD per transaction.
This limit was permanently raised from its historical $100 CAD threshold to allow Canadian consumers to tap for larger purchases, including full grocery carts and retail orders. However, specific boundaries apply depending on how the customer presents the payment:
Physical Debit Cards
A customer tapping a physical plastic card can spend up to $250 CAD in a single transaction. If a retail total reaches $250.01 CAD, the terminal will prompt the customer to insert their chip and enter their 4-to-6-digit PIN.
In addition to the per-transaction limit, financial institutions enforce cumulative limits. Cardholders have an internal counter (usually between $200 CAD and $500 CAD in cumulative tap transactions). Once that ceiling is met without PIN entry, the terminal requires a physical chip insertion to verify the legitimate cardholder, resetting the counter.
Mobile Wallets (Apple Pay and Google Pay)
When a customer loads their Interac debit card into Apple Wallet or Google Wallet, the transaction uses Consumer Device Cardholder Verification Method (CDCVM). Because the customer authenticates using biometric security (Face ID, Touch ID, or fingerprint) or a device passcode, many Canadian banks treat this as equivalent to a PIN entry. Consequently, smartphone taps often exceed the physical $250 CAD card limit, allowing higher-ticket contactless debit sales at the checkout counter.
Why should Canadian retailers encourage Interac tap over credit?
Encouraging your customers to tap debit instead of credit directly increases your bottom-line profitability and eliminates checkout friction.
- Massive Margin Protection on Larger Baskets: Because Interac is billed as a flat transaction fee, your processing overhead remains unchanged whether a customer spends $15 or $240. For businesses with ticket averages over $50 CAD—such as specialty boutiques, dental clinics, repair shops, and dining establishments—shifting transaction volume from credit cards to Interac debit saves hundreds or thousands of dollars each month.
- Protection Against Chargeback Fraud: Friendly fraud and chargebacks are persistent hazards with card-not-present and credit card transactions. Interac transactions are verified in real time against existing bank balances. Once authorized, the transaction is definitive; customers cannot call their bank weeks later to claim an unauthorized charge simply because they regret a purchase.
- Queue Busting Speed: Contactless debit transactions settle across the terminal screen in less than two seconds. For high-volume morning rushes in cafés, bakeries, or fast-casual concepts, shaving 10 to 15 seconds off every transaction by avoiding chip inserts and PIN delays keeps customer queues moving quickly.
What hardware do you need to accept Interac tap payments?
To process Interac debit contactless payments, you need an NFC-capable payment terminal configured with Canadian debit cryptographic keys and certified for Interac Flash processing.
While older credit-only terminals or legacy dial-up units lack the compliance requirements for current debit tap protocols, modern businesses use cloud-enabled smart terminals that function independently over Wi-Fi and 4G/LTE cellular connections.
Through Tap2Pay, businesses deploy industry-leading hardware like PAX smart terminals. These feature-rich devices provide ultra-fast NFC readers, vibrant touchscreen displays, high-speed built-in receipt printers, and automatic network switching between cellular data and Wi-Fi. Because they operate autonomously, your team can process sales anywhere—at a checkout counter, curbside, or off-site at Canadian markets and pop-up events. Explore our full hardware lineup by visiting our terminals.
Common Interac tap technical issues and how to fix them
Even with an ultra-reliable payment infrastructure, terminal operators occasionally encounter tap declines. Understanding these common scenarios helps your staff guide customers without delay:
- "Card Read Error" or Repeated Beeping: This usually happens when a customer taps their card outside the terminal’s antenna range or pulls it away too quickly. The NFC antenna is typically centered around the display screen or at the top of the device. Ensure the card rests stationary within two to three centimetres of the icon for a full second.
- "Insert Card" / "PIN Required": When the terminal screen requests a chip insertion, the customer has either exceeded their $250 CAD single-transaction limit or surpassed their bank’s cumulative contactless spending threshold. Advise the customer to insert the chip into the base of the terminal and enter their PIN to reset their bank’s fraud counter.
- "Application Not Supported" on Foreign Cards: Tourists or international visitors carrying foreign bank cards often attempt to tap what they believe to be a standard debit card. International bank cards operate over distinct debit rails (such as Maestro, Visa Debit, or private national switches) that do not route across Interac. In these instances, the customer must insert their chip so the terminal can process the transaction through the international Visa or Mastercard interchange system.
Frequently Asked Questions
Can customers use Interac tap with mobile wallets like Apple Pay and Google Pay?
Yes, Interac debit integrates fully with Apple Pay and Google Pay across all major Canadian financial institutions. Customers add their Canadian bank debit cards to their digital wallets and hold their smartphone or smartwatch over the payment terminal to complete their purchase.
Are Interac tap payments subject to chargebacks like credit cards?
No, Interac tap transactions do not carry the traditional chargeback risk associated with credit card networks. Because debit transactions require real-time electronic fund authorization directly from the cardholder's bank account, funds are definitively transferred and cannot be disputed via standard credit card chargeback mechanisms.
What is the maximum dollar limit for an Interac tap payment in Canada?
The standard contactless tap limit for physical Interac cards in Canada is $250 CAD per transaction. Purchases exceeding $250 CAD require the customer to insert their chip and input their PIN. However, transactions conducted through mobile wallets with biometric authentication can often exceed $250 CAD depending on the issuing bank.
How quickly do funds from Interac debit tap transactions reach my business account?
Funds processed over the Interac debit network are typically deposited into your merchant commercial bank account within one to two business days. Some providers, including Tap2Pay via its Nuvei processing architecture, offer next-day or accelerated settlement schedules to ensure steady cash flow for your business. Find answers to common merchant questions on our FAQ.
Upgrade your checkout with cost-effective debit processing
Accepting Interac tap payments is essential for any Canadian merchant aiming to meet consumer expectations for speed, convenience, and transaction security. By prioritizing contactless debit over costly, rewards-heavy credit cards, your business can significantly reduce processing fees while protecting operations from chargeback fraud.
Tap2Pay equips Canadian businesses with robust PAX smart terminals, zero hidden fees, flexible month-to-month terms, and dedicated bilingual English and French customer support. If you are ready to eliminate excessive processing fees and streamline your checkout counter, call 1-800-455-9090, email info@tap2pay.ca, or get a free quote today.