Switching Payment Processors: A Checklist for Canadian Merchants
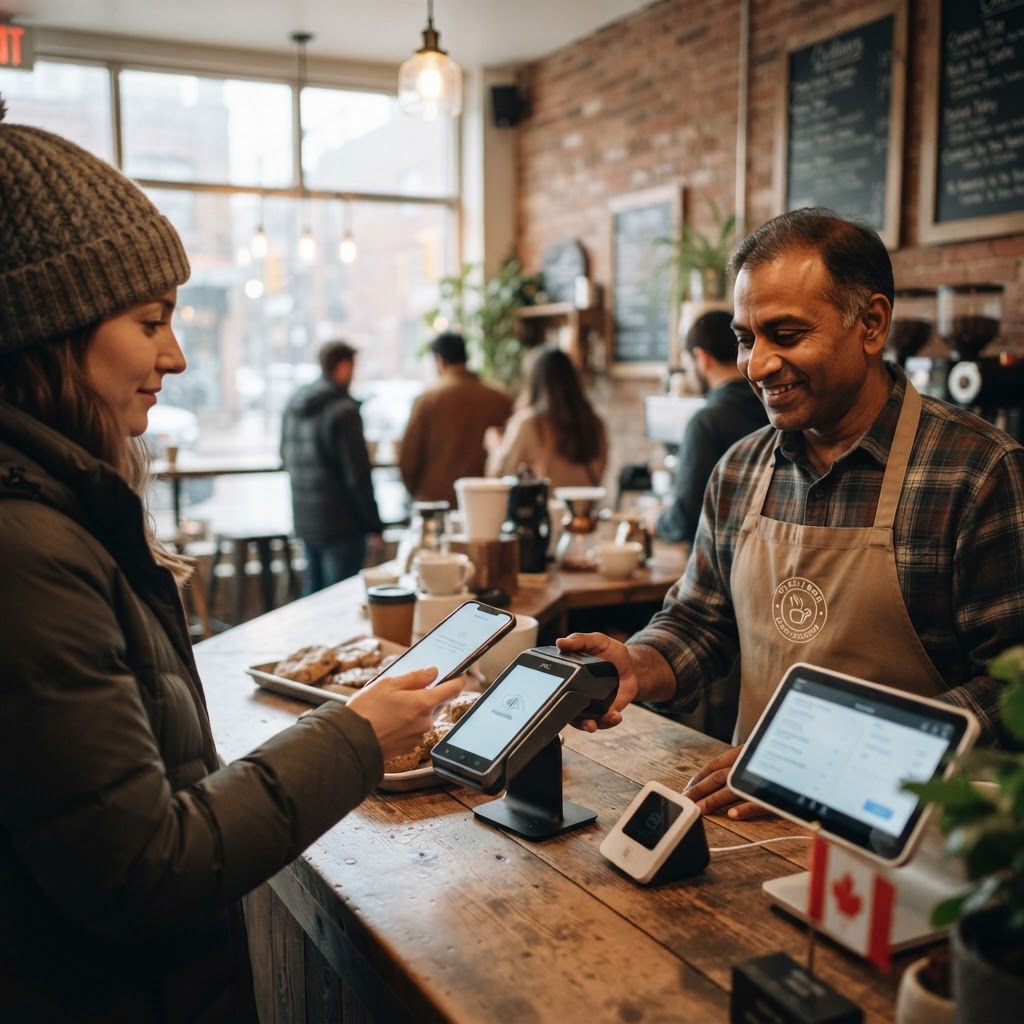
Switching credit card processing for small business Canada involves evaluating your current effective rate, identifying hidden fees in tiered pricing models, and ensuring your hardware supports modern Canadian payment standards like Interac Flash. By following a structured migration plan, merchants can reduce their overhead by 15% to 30% while upgrading to more reliable, transparent payment technology that complies with the Canadian Code of Conduct.
Key takeaways
- Interchange-plus pricing is the most transparent and cost-effective model for Canadian merchants, as it separates the actual cost of the transaction from the processor's markup.
- The Code of Conduct for the Credit and Debit Card Industry in Canada allows merchants to cancel their contracts without penalty if a processor increases fees or adds new ones, provided notice is given within a specific timeframe.
- Interac debit transactions in Canada typically carry a low flat fee rather than a percentage, making them significantly more affordable to process than credit cards for most small businesses.
- Modern PAX smart terminals are the industry standard for Canadian merchants, offering superior security, high-speed connectivity, and full support for contactless "tap" payments.
How much does credit card processing cost in Canada?
The cost of credit card processing for small business Canada typically ranges from 1.5% to 3.5% per transaction, depending on the pricing model, the type of card used (e.g., basic vs. premium rewards), and the method of entry. In the Canadian market, these costs are primarily driven by interchange rates set by card networks like Visa and Mastercard, which are then passed through to the merchant by the processor.
Understanding your "effective rate"—the total fees paid divided by your total processing volume—is the only way to truly measure your costs. Many Canadian merchants are surprised to find their effective rate is much higher than the "teaser" rate advertised on their monthly statements. This often happens because of hidden fees, such as monthly minimums, statement fees, or PCI compliance penalties.
At Tap2Pay, we believe in total transparency. We provide a detailed analysis of your current statements to show exactly where you are overpaying. By moving merchants to a transparent pricing model with no hidden fees, we typically help Canadian businesses save 15% to 30% on their monthly processing costs. You can view our straightforward pricing to see how we compare.
What is the difference between Interchange-plus and Tiered pricing?
Interchange-plus pricing is a model where the merchant pays the exact cost of the transaction (the interchange fee) plus a fixed, transparent markup from the processor. In contrast, tiered pricing bundles transactions into "Qualified," "Mid-Qualified," and "Non-Qualified" buckets, which often allows processors to hide higher margins by routing transactions into more expensive tiers.
For a small business in Canada, tiered pricing is almost always more expensive. A "Qualified" rate might look low, but very few modern cards—like premium travel rewards cards or corporate cards—actually qualify for it. This results in the majority of your transactions being downgraded to "Non-Qualified" rates that can exceed 3% or 4%.
| Feature | Interchange-Plus Pricing | Tiered Pricing | | :--- | :--- | :--- | | Transparency | High: Every fee is broken down by card type. | Low: Fees are bundled into vague categories. | | Cost | Lower: You pay the actual cost plus a small margin. | Higher: Processors pad the "tiers" for extra profit. | | Predictability | Consistent: The markup never changes. | Volatile: Rates depend on how the processor labels the card. | | Best For | Growing small businesses and mid-market firms. | Micro-merchants with very low volume. |
Tap2Pay exclusively uses transparent pricing models powered by Nuvei-powered processing. This ensures that our Canadian clients always know exactly what they are paying for, without the frustration of "non-qualified" surcharges appearing on their statements.
How do I switch payment processors without disrupting my business?
To switch payment processors without downtime, you must secure your new merchant account and hardware before terminating your existing contract, ensuring a "parallel run" period where both systems are functional. A common mistake is cancelling the old service before the new terminals arrive, which can lead to days of lost revenue if there are shipping delays or setup issues.
The migration process should follow these specific steps:
- Review your current contract: Check for liquidation damages or early termination fees. Under the Canadian Code of Conduct, you may have a window to exit if your rates were recently changed.
- Apply for a new account: Submit your application and go through the underwriting process. This usually requires 1-2 years of processing history or bank statements.
- Order and test hardware: Ensure your new terminals are configured for your specific business needs.
- Train your staff: Familiarize your team with the new interface, especially for processing Interac debit and contactless payments.
- Close the old account: Once the new system is running smoothly, send a formal cancellation notice to your previous provider and ensure you receive written confirmation.
What Canadian regulations protect merchants when switching?
The Code of Conduct for the Credit and Debit Card Industry in Canada protects merchants by requiring clear fee disclosure and providing the right to exit contracts if fees are increased or new fees are added. This regulatory framework, overseen by the Financial Consumer Agency of Canada (FCAC), is designed to ensure that the Canadian payments ecosystem remains competitive and fair for small businesses.
One of the most important aspects of the Code is the requirement for processors to provide 90 days' notice for any fee increases. If a processor raises their rates, the merchant has the right to cancel their contract without penalty within 90 days of that notice. This is a powerful tool for small businesses looking to escape high-cost legacy contracts.
Tap2Pay is a proudly Canadian company that fully adheres to these standards. We provide bilingual English/French local Canadian support to help our clients navigate these regulations. Whether you are in Quebec or British Columbia, our team is available at 1-800-455-9090 to ensure your transition is compliant and stress-free.
What hardware should a Canadian small business use?
Canadian small businesses should prioritize PAX smart terminals that support Interac Flash, EMV chip technology, and high-speed connectivity (Wi-Fi or 4G) to ensure fast, secure checkouts. In Canada, the ability to process Interac debit via "tap" is essential, as it is the preferred payment method for millions of consumers.
Legacy terminals are often slow, prone to connection drops, and lack the security features required for modern PCI compliance. Smart terminals, such as the PAX A-series, offer a smartphone-like interface that is intuitive for staff and customers alike. These devices also handle the higher contactless limits now common in the Canadian market, allowing for faster throughput during peak hours.
We provide our merchants with state-of-the-art PAX smart terminals that are fully integrated with our Nuvei-powered backend. These devices are designed for the Canadian climate and consumer habits, ensuring that whether you are running a boutique in Montreal or a service business in Toronto, your hardware will never be the bottleneck in your sales process.
Frequently Asked Questions
Can I surcharge credit card fees to my customers in Canada?
Yes, as of October 2022, merchants in most of Canada (excluding Quebec) have the option to add a surcharge to credit card transactions to offset processing costs. However, you must provide 30 days' notice to your card brands and clearly disclose the surcharge to customers at the point of checkout.
How long does it take to switch to a new processor?
The entire process, from application to having new hardware in hand, typically takes between 3 to 7 business days. Underwriting usually takes 24-48 hours, while shipping for new payment terminals depends on your location within Canada.
What is Interac Flash and why does it matter?
Interac Flash is the contactless version of Interac debit in Canada. It is critical for small businesses because it offers the fastest checkout experience and typically carries much lower fees than credit card "tap" payments, helping to keep your overall processing costs down.
Do I need a long-term contract for credit card processing?
While many legacy providers in Canada still try to lock merchants into 3-year or 5-year terms, modern processors offer much more flexibility. You should look for providers that offer no long-term contracts, allowing you to earn your business every month through service and fair pricing rather than legal obligation.
Switching your credit card processing for small business Canada doesn't have to be a complex or risky endeavour. By focusing on transparency, modern hardware, and a clear understanding of the Canadian regulatory landscape, you can significantly reduce your overhead and improve your customer experience.
If you are ready to stop overpaying and start growing, our team is here to help. We offer a no-obligation statement analysis to show you exactly how much you can save by switching to a fairer, more transparent partner.
Get a free quote today and see why Canadian merchants are making the switch to Tap2Pay.